Sunday, November 29, 2015

Question and Answer Time! Down Payments


"How much down payment will I need?" I heard this question again yesterday.  I get it a lot.

The short answer is, it depends. Of course, if you're asking, then you probably prefer the long answer.

It depends on the type of property you're trying to buy, the value of the home, your credit scores, and the type of loan you want and for which you can qualify.  Are you buying an investment property?  A lender will probably require 20-30% down.  A primary residence you'll live in?  Typically you'll need 5 to 20% for a conventional loan.  In 2014, one in five borrowers paid less than 10% down for a conventional loan.  There are, however, some popular lower-down-payment, non-conventional alternatives.  A common alternative is a loan backed by the Federal Housing Administration (FHA), which requires only 3.5% down.  If you meet their eligibility requirements, a Veteran's Administration (VA) loan requires NO money down.  If you are purchasing a home in a rural area, and meet other US Department of Agriculture (USDA) requirements, USDA also offers a no-money-down loan.

Home buyers can also check out down payment assistance programs, such as that offered by the North Carolina Home Finance Agency.  If you qualify, you my be able to obtain an interest-free, potentially forgivable second mortgage up to 5% of the first mortgage loan amount.  Check out the NCHFA website at www.nchfa.com.  (I highly recommend first-time home buyers also look at the NCHFA Mortgage Credit Certificate as another source of potential savings!)

Keep in mind that with most loans, if you want to avoid paying for Private Mortgage Insurance (PMI), you may need to pay 20% down. PMI protects the lender in case a borrower defaults.  Depending on credit scores and interest rates, the PMI typically runs $30-$70 per month for every $100,000.  On a conventional loan, this monthly PMI payment goes away when the loan-to-value (LTV) ratio hits 80%.  (In other words, if you bought a home worth $100,000, paid $10,000 down, and took out a loan for $90,000, the LTV ratio would be 90%.  When your loan principal has been paid down to $80,000, the LTV would be 80%.)   VA and FHA also have mortgage insurance payments for their loans, but these payments last for the life of the loan; they never go away.

Bottom line:  As soon as you become interested in buying a home, your first step should be to sit down with a mortgage broker.  (Let me know if you need a recommendation.  I know some good ones!)  A good mortgage broker will help you understand what your best options are, and what you need to know before you even start looking for your dream home -- like how much you can realistically afford and what to save for a down payment.


The Cost of Paying PMI vs the Cost of Waiting to Buy


Friday, October 16, 2015

Understanding TRID - what you need to know


Are you familiar with the change that occurred in the world of real estate and mortgage lending starting October 3, 2015? If you apply for a mortgage loan after October 3, this change -- the implementation of TRID -- will apply to you. For both buyers and sellers, it's important to understand not just the new documents introduced by TRID, but how new timelines set by TRID could impact your closings.  

TRID is an acronym for Truth-in-Lending Act/RESPA Integrated Disclosures. It has a worthy purpose -- to make loan documentation easier to understand for the consumer, less cumbersome and more transparent. There may be a few potential hiccups, however.

TRID replaces the “Good Faith” and “Truth In Lending” documents previously issued by lenders with a new document called a “Loan Estimate.” The Loan Estimate is easier to read and is probably an improvement over the old documents. Under the new guidelines, lenders must provide a potential borrower with the Loan Estimate no later than three days after he/she submits a loan application.

The other document TRID requires, and that is the cause for some concern, is the Closing Disclosure. This document replaces and combines the HUD-1 and other closing statements in a format intended to be easier to understand. Borrowers must receive this Closing Disclosure three business days (Saturdays and Sundays not included) before they can sign loan documents at the closing. This gives the borrow a chance to thoroughly review this document before the closing. Previously, the HUD-1 only needed to be in the hands of he borrower the day before the closing.

Because every number on the Closing Disclosure must be accurate, lenders will need to have loan documents in title three business days sooner than they do now. This also puts pressure on title companies/real estate attorneys to get the title work done earlier. If there is any error discovered in the numbers in the Closing Disclosure, the Closing Disclosure must be re-drawn and the three-day waiting period starts all over. Under TRID guidelines, any delay in closing becomes at least a three-day delay. A buyer who had hoped to move in immediately after the initially planned closing will need to have an alternative plan to accommodate a delay.

It's also worth noting that it is unlikely a client hoping to do same day closings on their home for sale and a new home purchase will be able to do this under these new guidelines.  It may be possible, but is not likely.  As a real estate agent, I'm preparing my clients for the fact they need to plan about a week contingency in between closings.

Below is the link to an article from one of my favorite real estate investment website, BiggerPockets.com, with useful additional information about TRID.

http://www.biggerpock...­

If you have additional questions about TRID, call or drop me a note.


Cheers

Mary Lynn Blake

Saturday, November 1, 2014

Wooing the Buyer

       Showcasing your Home at its Best    

You can sell almost anything -- and quickly -- if the price is low enough. But most people putting their home on the market understandably want the most they can get for it, in a reasonable amount of time. For that to happen, you need to take steps to make your house stand out from the competition (in a good way!) Don't get me wrong -- setting the right price is absolutely essential! But you need to woo the buyers also -- and you do that by making your home as appealing as possible.  Here are some tips for showcasing your home at its best.

First Impressions

First impressions are important! From personal observation (there have been studies, too; don't just take my word for it) I know most buyers make up their mind about a house within just a few minutes. Two new studies from the Society for Personality and Social Psychology in Austin, Texas confirm that first impressions are very hard to dislodge.  (A second part of this study says most people's snap judgements are pretty accurate -- guess you CAN judge a book by its cover.) So what are the basics of making a good first impression with your home?

...What's outside                                                                           

A good first impression starts with the curb appeal.  Stand in front of your house and look at it critically. What is the yard, front porch, windows, front door, etc. saying to the potential buyers as they walk up? Are they at the well-maintained home of an owner who is house-proud? A tidy yard, healthy plants, repaired fences, and exterior paint are places to start.  Do your shrubs and trees need trimming? Flowers in pots can provide a welcoming pop of color.  I love bright yellow for its energy and making your house stand out. But you must keep flowers watered, dead-headed when necessary, and looking healthy.  Withered, weedy plants are off-putting.  So are plastic flowers to many people, so pack those away, as well as that collection of garden gnomes. Your front porch needs to be spotless (no spider webs!), because that's where the buyer pauses before opening the door.  Is your doorbell rusty? Are house numbers crooked? Does the door need a fresh coat of paint? Do the lights work? Do you have a clean welcome mat?

...What's inside

Now step into your house, and pay attention to where your eyes are first drawn.  Is that what you want your buyers to see first when they walk in? What do you want it to be? In every room, consider what you want the focal point to be. You can guide potential buyers through your home visually, emphasizing what should be the focal points, by furniture place, color, home accents, strategically placed mirrors, etc. If you're having a problem being objective about your home, ask a friend or your agent to help you.  A professional stager can be a good investment.

Smell is almost as powerful as sight when it comes to first impressions.  Most people simply don't know what their homes smell like -- they're used to it.  Have an honest conversation with your Realtor or a friend about how your home smells, especially if you have pets or smoke. You may need to consider renting an air scrubber or taking other actions to eliminate odors, to include professionally cleaning carpets, drapes and upholstery. (I once desperately used an entire spray can of air deodorizer before an open house, with minimal results.) Some realtors like to use scented air fresheners, candles or even bake cookies to make the home smell enticing before an open house. Personally, I prefer no smell.  Some buyers may have allergies, don't like specific scents, or just start to wonder what you're trying to cover up

Love my Pets!

As long as we're speaking of pet odors...  My pets are my family and great companions -- but I know pets don't belong at a house showing.  They don't help to sell your house.  Many buyers don't want Fido jumping on them, or cat hairs sticking to their clothes. No one wants to pay good money for a house with pet stains and hair. Pay to have the house professionally cleaned, and take your pets to a friend's house during showing. A good idea is to hide any evidence of pets entirely.  Clean up any of those messes in the backyard, too!

Light it up!

Turn on the lights! Throw back the drapes! Buyers appreciate a bright, cheery home. Some other ways to bring in some extra light include cleaning the windows, removing screens and trimming back brush and trees around the windows.  Light colored paint also helps bounce and reflect light. Light, neutral-colored paints are also more appealing to most buyers.

Deferred maintenance

You've seen those minor defects that your property has accumulated over the years. It's important to address them before putting your home on view for potential buyers. Buyers appreciate a home that looks like it's been well tended by house-proud owners, and are less likely to go out of their way to look for issues. Also, keep in mind the buyer will be having a home inspection done once they've had an offer accepted. Did you know that the number one reason a home sale falls apart is due to problems discovered at a home inspection? (How to prepare for a home inspection will be the subject of another blog, I think!) If you're not sure about the condition of your home, spending a few hundred dollars for a pre-inspection could be well worth it.

Everyone wants more storage!

I've never once heard a potential buyer say storage wasn't important. Your home may actually have lots of closets and storage area, but if you've packed these spaces full, the buyer isn't going to perceive them as adequate for their own needs. Clean out the closets, storage shed and garage so the buyers can see what their getting. Remove at least half of what's there and organize the rest. If you need to, temporarily rent a storage facility or a storage POD.

Who's house is it?

Most potential buyers looking at homes want to see a blank slate where they can envision building
their own lives in their new home. To fit this ideal, you need to be prepared to remove yourself from the house -- emotionally and literally. It will help if you can tell yourself that where you are living now is no longer your home. (Does this seem too harsh? Then you may not be ready to move.) In order to create that blank slate for your buyers, you will need to make sometimes tough decisions to pack away your collectibles, take down family photos, paint over the darling mural in your daughters room and in general clear away everything that has made this house your home. You don't want your home to look 'sterile,' however. Carefully stage a few items that will have general appeal. Just remember, if it feels like your home, it can't feel like the buyer's home.

Out of sight

Along the same lines as the above, buyers really don't want to see your personal items. First of all, it's yucky. Also, a toothbrush, shampoo and damp towels stake out the bathroom territory as yours. Have a place to put all these personal items out of sight when you have a showing or open house -- in a bucket under the sink or a clothes basket you throw in the trunk of your car.  Here's a list items to get out of sight.  I'm sure you can come up with more -- just think of anything you wouldn't use/borrow from a stranger!
  • toothbrushes
  • bars of soap
  • razors
  • used towels, loofahs
  • dirty dishes
  • dish towels
  • combs, brushes, make-up
  • dirty clothes
  • pet supplies
By the way, LOCK away, or get them out of the house, anything that it would break your heart to have stolen. Also lock away prescription drugs, credit card info, personal or government documents, etc. You will have strangers in your home, and it is better to be safe than sorry.

Best foot forward

This can be the most tedious and frustrating part of selling your home -- and one of the reasons for wanting to sell as quickly as possible. Your home needs to be clean, staged and ready to show at a moment's notice. Hire a professional cleaner to get your home ready to show, and consider having cleaners come in regularly to keep the look up while your home is on the market.  It can be a great stress reliever knowing at least you don't have to worry about dust and toilet bowl rings.

Final thoughts

A good real estate agent will help you find the right strategy for selling your home based on the realities of the local market.  Find an agent you trust, and follow his/her advise as much as possible.   Good advise and these tips will help you sell your home faster and with less stress.  Good luck!

Mary Lynn Blake, REALTOR
Coldwell Banker Sea Coast Advantage
www.marylynnblake.realtor
maryblake@seacoastrealty.com

Serving your real estate needs in Wilmington NC
and it's beautiful beaches. 

Tuesday, July 22, 2014

Open House! Condo on the banks of the Cape Fear River

I'll let you use my binoculars.....

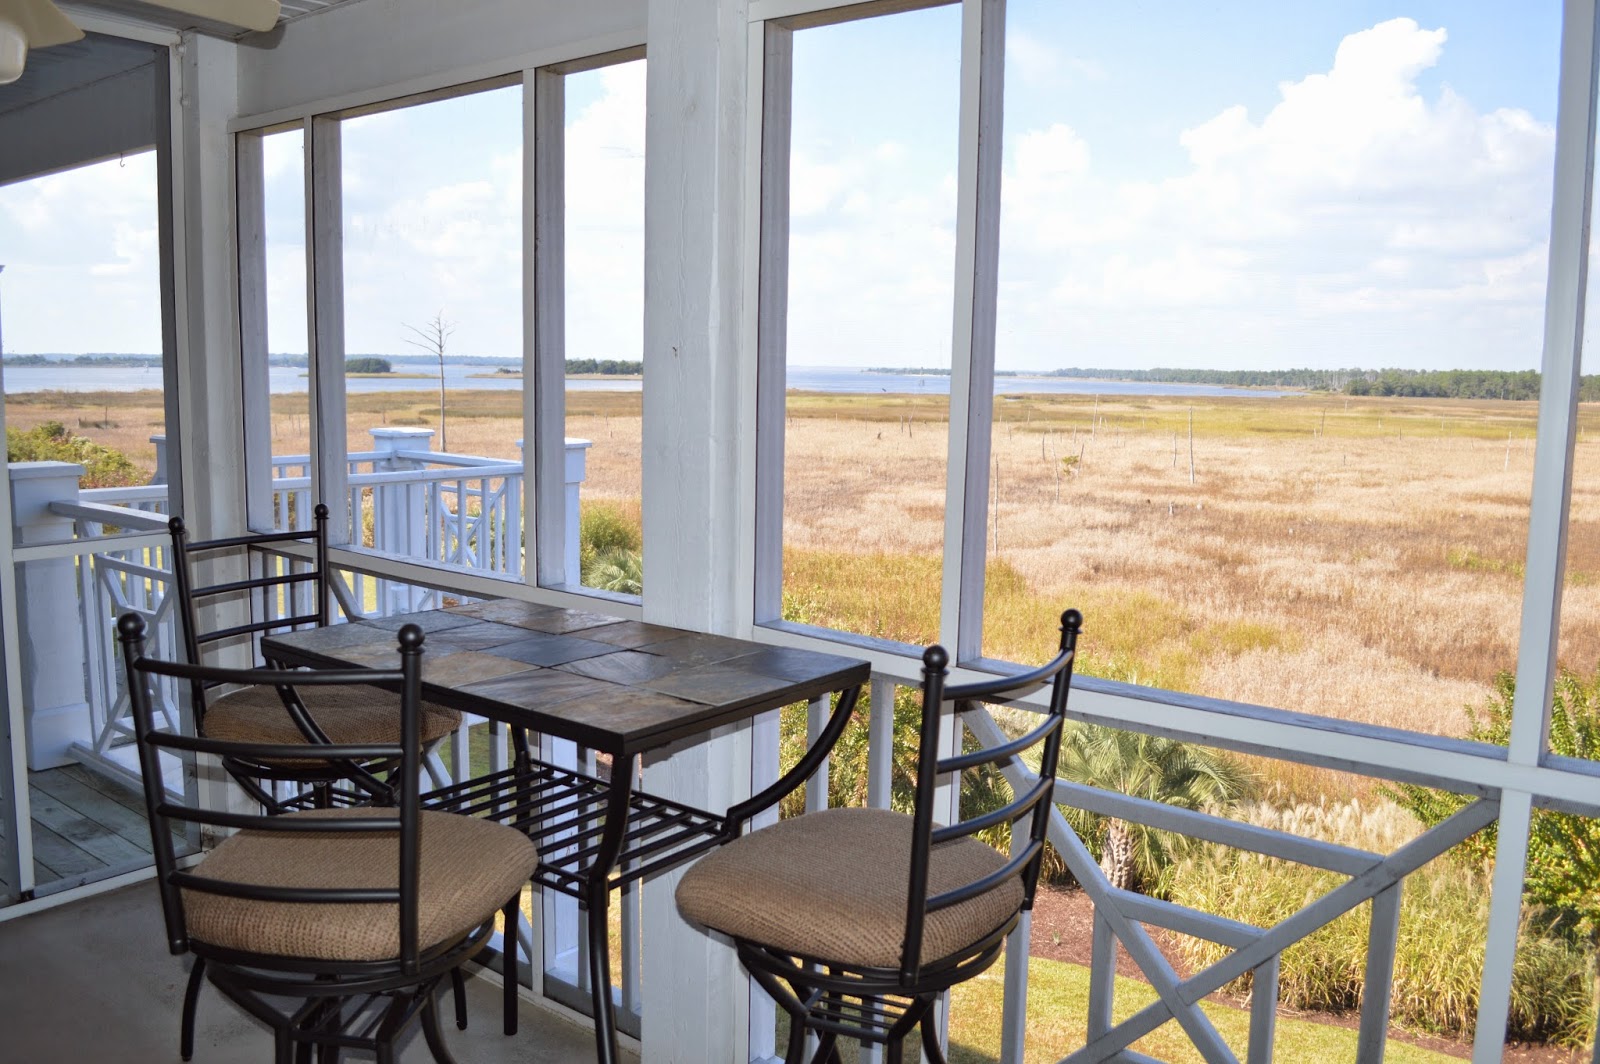
It's been awhile since I did an open house.   That's because my days (and nights) have been chock-a-block full showing homes and writing up contracts lately!  (Yeah! That's the kind of busy I love!)  But I've missed doing open houses.  Some agents are about as fond of open houses as a trip to the dentist, but I think they're fun and a great way to meet new clients, as well as help the seller, of course.  (Some day soon I'll write a blog about the good, the bad, and the ugly of open houses.) So, this weekend I'm thrilled to be able to host an open house at the gorgeous Turtle Cay condos.  These homes are just south of Wilmington NC, off of River Road, and have views to die for across the marshes to the Cape Fear River.  I could sit on this condo's balcony for hours and watch the birdlife and passing river traffic.   I expect, however, I'll be too busy with visitors to the open house to spend much time gazing through my binoculars this Sunday -- but I promise to let you borrow them if you come join us Sunday!   Here's my ad for the Open House:
      

OPEN HOUSE! 

Spectacular views of the Cape Fear River! 

104 Turtle Cay #10, Wilmington NC   
1-4 p.m. Sunday, July 27.

I'm bringing my birdwatching binoculars!  Come join me at my open house this Sunday afternoon in this lovely, renovated condo in the serene Turtle Cay community along the Cape Fear River.  Tastefully renovated with quality workmanship, this is a 2 bedroom condo that could easily have a 3rd bedroom. It has tray ceilings, a fireplace, new stainless steel appliances, tiled foyer, new flooring and paint. The views are to die for! Just a short 10 minute drive to Wilmington or a 5 minute drive to the beach. Only $164,900. Oh, by the way... This building is not in the flood plain, which will translate to lower costs for the owner.   See you there Sunday!


Saturday, July 5, 2014

June Real Estate News for the Wilmington NC Area

I've been crunching numbers again, folks, and here's what happened in June 2014 in the Wilmington area real estate market.  If you are planning on buying or selling a home, this is information you need!    

First of all, there's really excellent news for home buyers!  Mortgage rates are lower now than they were at this time last year!  This has come as a surprise to most lenders, who had predicted a steady rise.   (They are still saying it will soon start rising, of course.)  But for now, Freddie Mac's latest Primary Mortgage Market Survey says rates on 30-year fixed-rate is 4.12 percent with an average point of .05.    Last June, rates were 4.29 percent.

The good news for Sellers -- at least in New Hanover County:  The average price of sold homes in New Hanover continued a steady rise in prices -- March $247K, April $255, May $277K and  June $285k.  News is not so cheery in Pender and Brunswick counties (unless you're a buyer!), where average prices have stayed static or fallen slightly.   I believe one reason prices are rising faster in New Hanover is that the inventory is tighter, especially in the under $250k price range.  Market forces being what they are, less supply to meet demand means higher prices.  (see details about the Monthly Inventory Supply below.)   Thanks to a stronger stock market, sales in the New Hanover high-end homes and vacation properties has also pushed up the price averages.

Comparing traditional home sales (excluding the foreclosures and short sales), more homes were sold this year in June over last year at this time by 10%.  I also like to look at what's happening with foreclosures and short sales -- and it's clear the trend toward a normalizing real estate market is continuing:  Foreclosures in June 2014 are down almost 33% compared to June 2013, and short sales are down 45%.

Number of homes sold in the greater Wilmington area dropped a little between May and June, by 3.6%  (Historically, sold homes almost always take a dip in June -- not sure why!  maybe because kids are just out of school and families take vacation?)   As would be expected with these June sales figures, the "pending sales" (sales under contract but which would typically be expected to close within 60 days) were down significantly in May.  The good news is that pending sales in June were on a definite upswing (in May, 385; in June 423), which points to stronger sales in July.

Finally, let's take a look at the "Months Supply of Inventory" (MSI) in the greater Wilmington area.  As of June, the MSI was 6.96.  What does that mean? The MSI is an estimate of how long it will take for all the market's homes to be sold (or absorbed) based on how many homes are currently on the market and the rate homes have sold in the past (absorption rate).   MSI is simply used to compare the size of an inventory to the rate of sale. This is a great indicator of how balanced a market is.    Conventional wisdom says a balanced market has a monthly inventory of 5-7 months.  Less than 5 months supply means more competition among buyers, and is a seller's market; more than 7 months means an abundance of homes to choose from, and is a buyer's market.

MSI of 6.9 looks pretty balanced, although just on the cusp of being a Buyer's Market.  However, to get a better picture of the local market, it helps to break down the inventory by price range.  That tells us, across the greater Wilmington area, homes under $150K have an MSI of 5.4.   And, also looking at specific locales, in New Hanover County, homes in this price range have an MSI of 3.9 months; for homes between $150k and $250k, the MSI is 4.2!  That's well into Seller's Market territory.   It's tougher for home buyers in this price range to find a home, and may be more difficult to negotiate the price.  On the other end of the spectrum, the MSI for higher-end homes is still firmly in the Buyer's Market range, although the MSI has been dropping dramatically.  More high-end homes are selling, and they are selling faster than in previous months.

Here's a breakdown of MSI stats.  (note:  The most recent data is from May figures since I don't have all the MSI data for June yet.)

                                Apr      May     (May/New Hanover)
Under 150K             5.1       5.4            3.9
150k-250k                6.9       5.5            4.2
250k-350k                6.9       6.3            5.6
350k-450k               12.8      9.7            8.6
450k-550k               21.8     10.8           6.9
550k-1M                 22.2      17.4         11.9    

Hope you found this helpful.  


Wednesday, May 28, 2014

Feed Your Motivation!


“People often say that motivation doesn’t last. Well, neither does bathing – that’s why we recommend it daily.”  -- Zig Ziglar
It's easy to get discouraged.   It doesn't matter how pumped up or excited we were in the beginning, it's hard to sustain our enthusiasm and drive every day -- especially if we hit road bumps or just can't seem to move ahead as quickly as we'd like.  Motivation withers -- and with it the power to reach our dreams.
Feed your motivation!  Take a little time out of every day to read (or watch or meditate on!) something that motivates you, even if just for a few minutes.  What works for you?  That depends on you and the goals you're striving to achieve.  There are a wealth of books, blogs, videos and magazines on topics that will be specific for your goals.   There are likely people you can depend on to lift you up when you need a pep talk or advice.  Call them!  (although maybe not every day, unless it's your Mom, of course.)  For some, their highest and best motivation comes from their Bible.   Whatever it is that will keep your motivation strong and your goals clearly in sight, set aside a little time in your schedule every day to do it.  

But they that wait upon the LORD shall renew their strength; they shall mount up with wings as eagles; they shall run, and not be weary; and they shall walk, and not faint.  Isaiah 40:31

Tuesday, May 20, 2014

Dangerous Statistics   

 or 
Local Real Estate Market Trends Revisited


Then there is the man who drowned crossing a stream with an average depth of six inches.  ~W.I.E. Gates


Statistics are a dangerous thing.  Take the stats recently published by the local Wilmington Regional Association of Realtors (WRAR) about our local real estate market and I think you'll see my point. According to WRAR, when comparing April 2013 to April 2014, residential home sales declined 5.61%.   Pretty cut and dried, it seems.   Anyone looking at these figures, as published, would be excused for thinking real estate brokers all over town should be wailing and gnashing their teeth over a stagnant market.    We're not!  Or, at least shouldn't be.  And here's why...

When you pull those figures apart, a different and more realistic picture emerges of the market in the Wilmington area.  In fact, what's happening is that the market is 'normalizing.'

Break homes sales down by category and you find it is only distressed sales -- foreclosures and short sales -- that have declined drastically since this time last year.  Comparing the three-month period Feb-April 2013 and the same period in 2014, sale of bank-owned homes declined by 22%, and short sales by 38.5%!  By contrast, the non-distressed, traditional sales of residential properties in this same period  increased by 8.3%.   That's a sign of a healthier market.

Similar real estate activity is happening on a national level.  This chart shows sales activities by category looking at national averages for first quarter of 2014.


What else does this mean?

As any real estate investor who looks for uber cheap properties to buy, renovate and flip can tell you, the available distressed properties are drying up.   Improvements in the economy and better options for refinancing have resulted in fewer foreclosures and short sales flooding the market, as they did not that long ago.  In the Wilmington area in April 2013, there were 243 foreclosures on the market; in April 2014 there were only 198.  Appraisers are much less likely these days to have to include distressed sales in their appraisal calculations for homes.  That's good news for the average homeowners, who are watching the value of their homes edging up again.  Some who have been under water on their mortgage loans are finally seeing a chance to break the surface again.  Comparing April 2013 and April 2014, the median sales price of a home increased by 11.03% in the tri-county area near Wilmington.  Not bad!

Other factors may also contribute to the increase in the price of homes locally.  Demographically, Brunswick is the fastest growing county in North Carolina, with New Hanover and Pender top contenders as well.   The employment rate has also been slowly but steadily improving, putting homeownership within reach of more families.  That means more demand for homes -- good news for sellers and for builders.

The bad news for buyers -- besides expecting to pay a little more now -- is that inventory for homes is tightening up, especially properties under $250,000.  Expect to see more multiple offer situations with well-priced, well-kept homes.  There are many homeowners in the Wilmington area who may want to sell, but won't be adding their homes to the for-sale inventory any time soon because they still owe more on the loan than the home is worth.  (I've heard more than 20% of local mortgages are still upside down, but can't vouch for this figure.)  Local builders are busily playing catch-up to provide new homes after many years of little or no building activity.

Mortgage rates are also on their way up; and, although still low by historic standards, increased rates mean less buying power for buyers.  (Freddie Mac estimates interest rates will be almost 6 percent by 4th quarter of 2015.)   Qualifying for a loan can still be a challenge, but some lenders are easing restrictions as they begin competing with each other for business again.

Thoughts on the market over the coming months:
    I think sales will continue to be good, with prices continuing to edge up over the coming months.   However, the strong buying frenzy we saw last spring/summer -- with buyers with pent-up property hunger trying to take advantage of extraordinarily low interest rates and prices --probably will not be repeated.  Higher interest rates and prices will tamp down sales some.   I expect the comparative stats to between last summer and this summer to be less dramatic as a result.   We'll just have to keep an eye on it.


WRAR statistics for residential sales as of April 2014

Categories/

Indicators

% Changes

Jan-Apr 2013 to Jan-Apr 2014

 Apr 2013 to 

  Apr 2014

Mar 2014 to Apr 2014
 Total Units Sold
-2.80%

-5.61%

+5.45% 
 Avg. Sales Price
+2.43% 

+3.37% 

+4.10% 
 Median Sales Price
+6.16% 

+11.03% 

+7.09% 
 Total Dollars
-0.44% 

-2.43%

+9.77%
 Days on Market
-3.70%

-1.47%

+2.29%
 New Listings
-3.02%

+11.66%

+12.26%

Note that total sales(traditional and distressed) increased significantly when comparing just the month to month period of March and April 2014.